Blog

  • Why Truck Accident Cases Are So Complicated

    Why Truck Accident Cases Are So Complicated

    Truck accidents involve far more than a simple collision between vehicles. The size and weight of trucks, the type of cargo they carry, and the number of parties connected to each vehicle create a complicated web of responsibilities. Drivers, trucking companies, insurers, and contractors can all share liability, making it challenging to determine who is accountable. Navigating insurance rules, federal and state regulations, and evidence collection adds layers of complexity.

    Understanding these factors early is essential for victims to protect their rights, preserve evidence, and seek fair compensation after a serious truck accident.

    Multiple Parties Involved

    One reason truck accident cases are difficult is the number of people who can share responsibility. A crash rarely involves just the truck driver. The trucking company that owns the vehicle, contractors handling the cargo, and even maintenance crews can all be part of the legal picture. Each of these parties brings a separate insurance policy, rules, and obligations.

    Insurance coverage adds another layer of complexity. Commercial trucking policies have higher limits than personal auto insurance, but they often come with strict conditions and exclusions. Determining which policy applies and how liability is shared requires careful review of contracts, policies, and accident reports. Seeking legal help after a truck accident early ensures that no detail is overlooked and the correct parties are held accountable.

    Federal and State Regulations

    Trucking is heavily regulated. Drivers must follow strict hours-of-service rules to prevent fatigue, and vehicles must undergo regular inspections and maintenance. These rules are critical in assigning responsibility, but they also make cases more complicated. Investigators need access to logs, inspection records, and maintenance reports to show whether a driver or company failed to follow the law.

    Any lapse in following these rules can become a key piece of evidence. For example, a missing maintenance record or a violated service hour limit can demonstrate negligence. Understanding these regulations requires experience and careful attention, which is why professional guidance is essential to avoid missing critical information.

    Determining Fault and Negligence

    Assigning fault in truck accidents is rarely straightforward. Large trucks leave behind physical evidence like skid marks and vehicle damage, but interpreting this evidence requires experts. Accident reconstruction specialists examine speed, vehicle weight, and collision patterns to show how the crash occurred.

    Driver behavior also plays a significant role. Fatigue, distraction, or impairment may contribute, but external factors like road conditions, weather, and actions of other vehicles must also be considered. Witness statements and black box data from the truck provide additional insights. All of this evidence needs to be collected and analyzed promptly to build a clear picture of responsibility.

    Complex Legal Procedures

    Truck accident cases follow detailed legal procedures that can overwhelm victims. Accident reports, medical records, and trucking logs are just the beginning. Statutes of limitations set strict deadlines, and missing a filing date can prevent a claim entirely. Comparative negligence rules may assign partial fault to the injured party, reducing compensation if not properly addressed.

    Negotiating with insurance companies is another challenge. Commercial insurers often have teams dedicated to minimizing payouts. Legal support ensures that claims are documented correctly, deadlines are met, and negotiations are handled strategically. Legal professionals help victims focus on recovery rather than becoming lost in paperwork and disputes.

    Financial Stakes and Long-Term Impact

    Truck accidents frequently result in severe injuries, long-term disability, or even fatalities. The financial consequences are substantial, including medical bills, lost income, property damage, and rehabilitation costs. In many cases, the stakes are much higher than in typical car accidents.

    Securing appropriate compensation requires careful calculation and a clear understanding of liability. Negotiations must consider not just immediate costs but future expenses and long-term care. The complexity of these claims makes professional legal guidance essential for protecting victims’ financial stability.

    How Legal Support Can Make a Difference

    Experienced truck accident attorneys provide critical support. They investigate the accident thoroughly, identify responsible parties, gather evidence, and handle communications with insurers. By managing these steps, attorneys allow victims to focus on recovery while ensuring that their claims remain strong.

    Early intervention is particularly important. Preserving evidence, reviewing compliance records, and documenting injuries promptly all strengthen a case. Accessing legal help after a truck accident early increases the chances of fair compensation and reduces the risk of errors that could jeopardize the claim.

    Final Thoughts

    Truck accidents present legal challenges unlike other vehicle crashes. Multiple parties, strict regulations, accident reconstruction, and complex insurance policies all combine to make these cases complicated. Victims face high financial and personal stakes, and navigating this process without guidance can be overwhelming.

    Professional legal support ensures that the right evidence is collected, deadlines are met, and claims are handled strategically. With proper guidance, victims can secure the compensation they need to recover and rebuild. The complexity of truck accident cases is significant, but careful planning and early legal assistance can make the path clearer and more manageable.

    Also Read
  • How to Choose the Right Prebuilt PC for Your Needs

    How to Choose the Right Prebuilt PC for Your Needs

    Investing in a prebuilt PC is a practical approach for many users, offering a blend of convenience and efficiency. Whether you are looking for a machine for gaming, professional work, or everyday tasks, the market offers a wide variety of options tailored to different needs. Choosing the best prebuilt computers for gaming and work can streamline your search for a reliable, high-performance system.

    With an abundance of manufacturers and configurations, picking the right prebuilt PC can feel overwhelming. Understanding core components and carefully assessing your needs will ensure your investment delivers both immediate satisfaction and future readiness.


    Assess Your Computing Needs

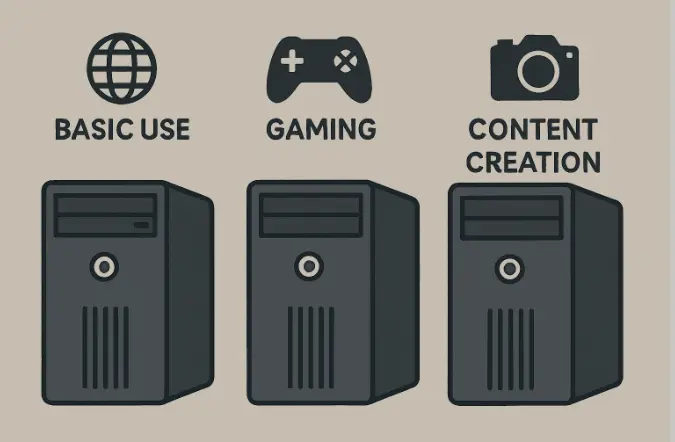
    Before selecting a PC system, it is essential to define your specific needs. Prebuilt systems cater to a range of use cases, from basic tasks to professional workflows. For basic tasks like browsing and email, integrated graphics and entry-level processors with 8 to 16 GB RAM are adequate. Gaming requires higher performance, emphasizing dedicated graphics cards (e.g., NVIDIA GeForce RTX, AMD Radeon) and capable multi-core CPUs. Content creators should prioritize powerful CPUs, 16-32 GB RAM, and fast SSD storage to efficiently handle photo editing, video production, and 3D rendering. Professional applications may require specialized features such as ECC memory and discrete GPUs to ensure stability in software environments, underscoring the importance of understanding software requirements.

    While reviewing potential purchases, it is crucial to ensure that the hardware specifications translate to real-world performance. Consider the environment and usage of the PC as well; if low noise is a priority, look for models with efficient cooling solutions, whereas aesthetic preferences might lead you toward options with RGB lighting or stylish tempered glass cases. Ultimately, the performance and design should align with daily needs and personal satisfaction in both work and leisure settings.

    Evaluate Component Quality and Specifications

    Every element in a prebuilt PC influences overall usability and future value. While headline features like CPU and GPU draw the most attention, other hardware like RAM, storage, and power supply units (PSUs) play significant roles.

    • Processor (CPU): Opt for the latest available generation from trusted brands like Intel or AMD. For multitasking and demanding programs, a multi-core processor improves speed and responsiveness.
    • Graphics Card (GPU): Gaming and creative applications require a dedicated GPU. Look for current models with established benchmarks in your intended uses.
    • Memory (RAM): A minimum of 16 GB of RAM is recommended for most users, though heavy multitasking or creative work may benefit from 32 GB or more.
    • Storage: SSDs provide quick boot times and data transfer speeds. If you need a large capacity for media or backups, supplement with an additional HDD.
    • Power Supply Unit (PSU): A reliable PSU is essential for hardware longevity. Ensure the PSU has sufficient wattage and comes from a reputable brand, as identified by user reviews and independent tech sites.

    Clarity about the brand and model of each component is important. Vague listings or undisclosed hardware versions can be a warning sign, indicating potential cost-cutting that may affect performance or future upgrades. Major publications like PCMag can help you verify specs and compare system performance.

    Another factor when evaluating a prebuilt system is cooling and airflow. Even if you aren’t overclocking or pushing components to their limits, sufficient cooling extends hardware life and minimizes performance throttling. Check whether the case has adequate ventilation and whether the manufacturer includes enough fans, or if aftermarket options are available for cooling upgrades. A well-cooled system also protects your investment by preventing long-term heat-related issues.

    Be Cautious of Proprietary Components

    Certain brands include non-standard or proprietary parts, such as power connectors or case layouts unique to that manufacturer. While these designs can streamline support or reduce costs initially, they commonly pose obstacles when it comes time to swap or upgrade hardware. It is generally beneficial to choose systems offering standard components, ensuring a smoother upgrade experience and easier access to replacement parts if needed.

    Understand Warranty and Support Options

    Most reputable prebuilt PCs include warranties and technical support. Evaluate the specifics of these offerings, including what is covered, response times, and whether coverage extends to onsite repairs or parts replacement. Good manufacturers stand by their products, and comprehensive support can provide peace of mind.

    Before purchase, consider whether the warranty covers shipping both ways and if there are authorized service centers nearby. Sometimes, support services offer remote diagnostics or scheduled technician visits, which can minimize your system’s downtime if issues arise. Having local support or reliable online assistance is an underappreciated value for long-term ownership, especially if you rely on the PC for your work or studies.

    Consider Future Upgradeability

    One drawback of many prebuilt PCs, especially compact or specialty designs, is reduced upgrade flexibility. Components such as motherboards, cases, and cooling solutions could use unique sizes or fittings. Before purchase, review which system components can be updated over time, such as additional RAM slots, extra storage bays, or PCIe expansion. Anticipating future needs can help you avoid replacing your PC sooner than expected.

    Even if you do not plan to upgrade right away, a forward-thinking choice lets you make economical improvements over the years, such as adding more memory or a better GPU when your needs change, rather than a costly full-system replacement. Some buyers also appreciate the ability to upgrade their PC for resale or repurposing in the future, making initial flexibility a smart investment.

    Research and Compare Options

    Once you understand your needs and the features available, spend time researching specific models. Compare specifications, price points, user reviews, and brand reputations. Paying close attention to feedback from current users and testing organizations is invaluable in identifying both strengths and weaknesses in real-world usage.

    Conclusion

    Choosing the right prebuilt PC is a process best guided by careful evaluation of your activities, hardware quality, and intended future upgrades. Thorough research across multiple reputable sources and transparency about system specs are core factors in finding a system that suits your budget and expectations. By following these steps, you will be better equipped to select a PC that performs reliably and stands the test of time.

    Also Read-

  • How Next-Generation AI Is Changing Portfolio Management

    How Next-Generation AI Is Changing Portfolio Management

    Artificial Intelligence is ushering in a new era for the financial industry, fundamentally reshaping portfolio management through automation, insight-driven strategies, and predictive analytics. Today, advanced platforms like Ridgeline.AI demonstrate how integrating AI with investment management can boost efficiency, streamline research, and enhance overall outcomes for both institutional and retail investors.

    By capturing complex market signals and analyzing vast datasets, AI is supporting asset managers in making faster and more data-driven decisions. It enables investors and managers to minimize biases, better manage risks, and optimize returns. The shift toward AI-powered investment tools is not just a matter of convenience; it is quickly becoming a competitive necessity in finance.

    Across the finance sector, AI-driven automation is reducing manual workloads associated with research and trading, while real-time monitoring and adaptive learning algorithms allow portfolios to dynamically adjust to changing market conditions. This ever-evolving technology pushes firms to stay ahead of the curve by leveraging powerful insights that were once out of reach to even the most skilled human analysts.

    As these developments continue to unfold, the landscape of portfolio management grows increasingly sophisticated and accessible, offering advanced tools previously reserved for elite asset managers to the broader investment community.

    AI Integration in Portfolio Management

    The adoption of AI technology within portfolio management is rapidly accelerating. Financial institutions and fintech startups alike are harnessing machine learning algorithms to sift through massive amounts of data, recognize emerging patterns, and implement investment strategies with greater accuracy. AI-driven tools provide capabilities far beyond human reach, with the ability to detect market trends and make split-second decisions that reflect evolving conditions.

    Through natural language processing and predictive modeling, AI is able to parse market news, financial reports, and social sentiment at unprecedented speeds. This allows portfolio managers to incorporate a broader array of data sources for a more holistic view of risk and opportunity. Integration with AI does not just bolster accuracy; it also lowers operational costs and enables greater scalability for firms managing large numbers of portfolios or client accounts.

    Enhancing Decision-Making with AI

    AI significantly amplifies the quality of decision-making in investment management. Machine learning models can identify subtle correlations within vast datasets, drawing connections between economic factors, financial statements, and behavioral trends that may be missed by traditional analytics. With access to real-time data and forecasting capabilities, portfolio managers are empowered to anticipate market movements and refine their investment strategies accordingly.

    For instance, AI can help managers quickly spot market anomalies, identify arbitrage opportunities, and dynamically reallocate assets in milliseconds, which reduces exposure to potential losses and boosts returns. Continuous learning features allow these algorithms to evolve alongside the market, improving both the timeliness and relevance of investment choices. Some of the most innovative investment firms are now leveraging AI as a central pillar of their portfolio strategy, leading to superior risk-adjusted returns and enhanced client satisfaction.

    Risk Assessment and Mitigation

    Effective risk management has always been a cornerstone of successful portfolio management. AI-driven tools now allow managers to evaluate risk in real time by examining market volatility, economic indicators, and asset correlations. These systems can run countless scenario analyses to estimate the impact of different events, helping managers to construct resilient portfolios that are better protected against sudden downturns or black swan events.

    AI’s predictive capabilities enable more granular risk assessments by uncovering hidden exposures and simulating crisis conditions. They also provide alerts for abnormal patterns in trading activity or market behaviors, enabling timely interventions that can prevent significant losses. By deploying adaptive risk models, modern portfolio managers can proactively adjust investment allocation and hedging strategies as conditions change.

    Real-World Applications

    Some of the world’s most prominent companies have integrated AI into their investment platforms to deliver a superior experience and stronger results. For example, Ridgeline’s AI-powered platform enables users to research and manage custom investable indexes with the help of algorithmic insights. This model empowers investors to construct diversified portfolios tailored to individual needs and market expectations.

    Another notable example is Microsoft’s revamped Foundry platform, which facilitates the development and oversight of AI agents in enterprise investment settings. Through features like unified data access and smart visualization tools, Foundry enhances collaboration and portfolio transparency. As these AI applications become more refined, they are progressively democratizing access to tools that help investors manage capital with confidence and agility.

    Challenges and Considerations

    Despite the many benefits, several challenges are associated with integrating AI into portfolio management. Data integrity remains a central issue, as the effectiveness of AI models relies on the breadth and accuracy of the underlying datasets. Incomplete or biased data can produce unreliable predictions, potentially harming performance or investor trust. Additionally, the complexity of AI systems raises important questions about the transparency and interpretability of automated decisions, which makes regulatory compliance a constant consideration.

    Asset managers must also establish safeguards against algorithmic biases and ensure adherence to ethical guidelines in their use of AI. Continuous monitoring, robust testing frameworks, and clear governance structures are critical for managing these concerns and building stakeholder confidence in AI-driven investment solutions.

    Future Outlook

    The trajectory for AI in portfolio management points toward a future characterized by even deeper integration and sophistication. Developments in generative AI, self-learning investment models, and hyper-personalized solutions will further empower managers and investors with unprecedented analytical tools and automation capabilities. As the technology matures, AI will enable more nuanced approaches to managing risk and capturing opportunity, potentially ushering in a new golden era of innovation in finance.

    Ultimately, next-generation AI is not simply enhancing existing practices; it is transforming the foundational principles of portfolio management, driving higher efficiency, smarter strategies, and broader accessibility to sophisticated investing.

    Also Read-

  • How Nutrition Supports Healthy Hair Growth in Women

    How Nutrition Supports Healthy Hair Growth in Women

    For many women, healthy, vibrant hair is more than just an aesthetic goal; it reflects overall well-being. While genetics and proper care play important roles, diet is a critical factor sustaining beautiful hair. Incorporating nutrient-rich foods and considering women’s hair products brands are effective strategies for enhancing hair strength and resilience from within.

    Eating a wide variety of whole foods provides hair follicles with the nutrients needed for optimal growth and helps minimize the risk of hair thinning and breakage. Even minor deficiencies in certain vitamins and minerals can spark noticeable changes, sometimes leading to dullness, brittleness, or shedding. Achieving lush, healthy hair goes beyond surface-level products and involves nourishing your body with essential nutrients, which are the true foundation of healthy hair.

    Many women discover that changes in their diet can transform hair texture, thickness, and shine. Understanding which nutrients are most beneficial, how to identify deficiencies, and which foods to choose empowers women to take a proactive role in hair care. Focusing on a nutrient-dense, balanced diet will not only revitalize hair but also support overall health.

    Establishing a nutritious diet and understanding your hair’s unique needs can maximize growth potential across different life stages.

    Protein: The Building Block of Hair

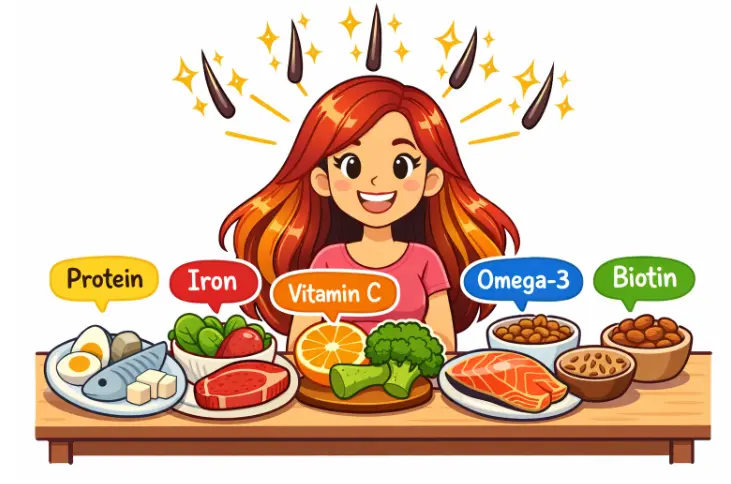
    Hair consists primarily of keratin, a protein that forms the structure and integrity of each strand. Without sufficient dietary protein, your body will prioritize vital functions over hair growth. This can diminish hair production and leave hair weak and prone to breakage. Include protein sources such as eggs, lean poultry, tofu, fish, and legumes in your meals to maintain strong, healthy hair. Ensuring your protein intake meets your daily requirements is the most reliable way to support hair resilience and growth.

    Iron: Essential for Oxygen Delivery

    Iron deficiency, especially common among women, can lead to slowed hair growth or increased hair loss. Iron enables red blood cells to deliver oxygen to every tissue, including the tiny blood vessels feeding your hair follicles. If your diet lacks iron, new hair may not obtain enough nutrients to grow properly. To boost iron intake, add iron-rich foods such as lentils, chickpeas, spinach, and lean red meat. Eating these alongside vitamin C sources can amplify their absorption in the digestive tract.

    Vitamin C: Enhancing Iron Absorption

    Vitamin C enhances the absorption of non-heme iron from plant foods, which is crucial for women following vegetarian or vegan diets. Additionally, vitamin C accelerates collagen production, giving hair enhanced strength and flexibility. Fresh fruits, such as oranges, strawberries, and kiwis, as well as vegetables like bell peppers and broccoli, are excellent choices to help you meet your daily vitamin C needs and fortify your scalp’s foundation.

    Omega-3 Fatty Acids: Nourishing the Scalp

    Omega-3 fatty acids keep the scalp moisturized and elastic, preventing dryness and flakiness that can hinder hair growth. These healthy fats are inherent to cell membranes and amplify circulation in the scalp, creating a thriving environment for follicle development. To reap these benefits, eat fatty fish like salmon, sardines, and mackerel, or include flaxseeds, chia seeds, and walnuts for a plant-based approach. A steady supply of omega-3s also helps fight inflammation, which can negatively affect hair.

    Biotin: Supporting Keratin Production

    Biotin, one of the B-complex vitamins, helps form keratin, the protein that forms the actual structure of hair strands. Deficiency is uncommon but can cause hair thinning and stunted growth. You can support your daily biotin requirements by eating a variety of eggs, almonds, sunflower seeds, and whole grains. Many women notice improved hair texture and shine after optimizing biotin intake, as this nutrient supports robust keratin formation and scalp health.

    Vitamin D: Stimulating Hair Follicles

    Vitamin D influences hair follicle cycling and may play a role in the creation of new hair follicles. Inadequate levels have been linked to certain types of hair loss, especially in women with limited sun exposure. Safe sun exposure, fortified foods, mushrooms, and oily fish are all ways to obtain more vitamin D. If you suspect a deficiency, consult your healthcare provider about testing and supplementation for optimal hair growth and overall wellness. For additional reading on the effects of vitamin D on hair, visit Healthline’s article on vitamin D deficiency and hair loss.

    Zinc: Maintaining Hair Tissue

    Zinc is involved in tissue growth and repair, including the renewal of hair follicles. A lack of zinc can result in hair shedding and delayed recovery from damage. Foods such as oysters, pumpkin seeds, beef, lentils, and cashews are rich in zinc. Because zinc also stimulates sebum production, it keeps the scalp hydrated and helps minimize hair dryness or brittleness.

    Vitamin A: Regulating Sebum Production

    Vitamin A supports the production of sebum, the natural oil that protects, moisturizes, and nourishes both scalp and hair. This oil acts as a barrier, preventing hair from becoming dry or brittle. Sweet potatoes, carrots, dark leafy greens, and cantaloupe are all significant sources of beta-carotene, which the body converts to vitamin A. Enjoying a range of colorful produce ensures your scalp remains in peak condition for hair growth.

    Conclusion

    Building a balanced, nutrient-rich diet is fundamental for maintaining healthy hair and preventing hair issues in women. By understanding and targeting specific hair needs with proper nutrition, paired with the right products, you can improve strength, texture, and growth from the inside out. Prioritize whole foods, lean proteins, healthy fats, and a spectrum of colorful fruits and vegetables to give your hair every opportunity to thrive and achieve its full potential.

    Also Read-

  • How Investors Can Protect Themselves From Securities Fraud

    How Investors Can Protect Themselves From Securities Fraud

    Investing can be a powerful way to build long-term financial security, but it also carries risks. Among the most significant dangers investors face is securities fraud, which can lead to devastating losses and erode confidence in the financial markets. Anyone looking to safeguard their assets should understand how to detect fraudulent activity and know where to turn for trusted support, such as a qualified securities fraud attorney in CA.

    Staying ahead of evolving scams and spotting deceptive tactics is vital in the modern investing landscape. Investors need to be proactive, both in conducting due diligence and recognizing the warning signs of fraudulent schemes. The more you know about these risks, the better equipped you will be to avoid them and protect your financial future.

    Understanding Securities Fraud

    Securities fraud involves illegal and deceptive practices carried out in the stock or commodities markets. Perpetrators often use false information or conceal material facts to manipulate investors. As a result, victims may make poor financial decisions, sometimes losing their life savings or retirement funds.

    This kind of fraud undermines trust in the investment system as a whole. Whether by misrepresentation of a company’s financial status or through sophisticated trading scams, fraud can have ripple effects well beyond individual investors, affecting entire markets.

    It is especially important for novice investors to recognize that while regulations are in place to protect market participants, fraudsters continuously adapt their methods. This means that the best line of defense is often a combination of personal caution and staying educated about current threats.

    Common Types of Securities Fraud

    • Insider Trading: This occurs when individuals use confidential, material information to trade a stock or commodity. Such actions give unfair advantages and are illegal under federal law. More details can be found in this Kiplinger article on insider trading.
    • Pump and Dump Schemes: Scammers artificially drive up a stock’s price using false or misleading statements. Once the price is inflated, they sell their own shares at a premium and leave other investors with losses when the price collapses.
    • Ponzi Schemes: Rather than actual investments generating returns, these schemes pay profits to earlier investors using funds from new participants. Eventually, the scam collapses, leaving most participants with significant losses.
    • Misrepresentation or Omission: Fraudsters may provide fake documentation or omit crucial details about a company’s financial health, misleading investors regarding the real risks or outlook of an investment.
    • Advance Fee Fraud: Scammers may ask for an upfront fee in exchange for exclusive opportunities, but once the fee is collected, the promised investment often fails to materialize or is entirely fictitious.

    Red Flags to Watch For

    Even experienced investors can fall victim to fraud, but there are specific signs that can help identify potential scams. First, investors should be wary of unrealistic promises of high returns with minimal or no risk, as these are often red flags. Additionally, high-pressure sales tactics may signal a fraudulent scheme; if there is pressure to make immediate investment choices, caution is advised. Another indication of potential fraud is the presentation of opportunities involving unregistered products or brokers who lack the necessary licenses.

    Investments that are confusing or overly complex can also reveal a lack of transparency, serving as indicators of potential deceit. Furthermore, requests for payments to personal accounts, particularly via wire transfers or cryptocurrency, should be treated with suspicion. Another common tactic used by fraudsters is discouraging investors from seeking second opinions or keeping conversations about the investment discreet. If investors are urged not to discuss the opportunity with friends, family, or professionals, it is essential to heed this as a significant warning sign of possible fraud.

    Strategies to Protect Your Investments

    1. Conduct Thorough Research: Take time to investigate any opportunity, reviewing public records and financial statements using reliable databases, such as the SEC’s official resources.
    2. Verify Credentials: Ensure that your advisor or broker is registered with the SEC or FINRA and has a clean record. You can check professional backgrounds and disciplinary history easily online.
    3. Be Skeptical of Unsolicited Offers: Treat unexpected opportunities with caution, especially those promoted through emails, cold calls, or social media messages.
    4. Understand the Investment: Ensure you know exactly how the investment works, the risks involved, and how returns will be generated. Never invest in something you do not understand.
    5. Consult Professionals: Reach out to a reputable financial advisor or securities attorney for unbiased, qualified advice before making substantial investment decisions.
    6. Keep Detailed Records: Save all correspondence and documentation related to your investments. Should a dispute arise, having a clear paper trail can be invaluable when pursuing legal recourse or filing complaints with regulators.
    7. Diversify Your Portfolio: By spreading your investments across various asset classes and companies, you can reduce the potential impact of any one fraudulent event or failed investment on your overall finances.

    Legal Recourse for Victims

    If you suspect you are a victim of securities fraud, prompt action is crucial to mitigate losses and improve recovery prospects. First, report the incident to relevant authorities such as the Securities and Exchange Commission (SEC), the Financial Industry Regulatory Authority (FINRA), or your state’s securities regulator. Next, it’s advisable to consult an attorney specializing in securities law to discuss potential recovery strategies and the possibility of legal action. Keeping an eye out for class-action lawsuits or settlements aimed at compensating investors affected by fraudulent behaviors is also important. Furthermore, closely monitor your investment accounts for any suspicious activity; this vigilance enables early detection of unauthorized transactions and helps document misconduct for legal purposes. In cases of widespread fraud, regulatory bodies may establish compensation funds or provide mediation services to support victims. Consulting with a seasoned attorney can help identify all available options, such as participation in class actions or negotiating settlements with responsible entities.

    Staying Informed and Vigilant

    Staying engaged and keeping up to date with current investment scams is one of your best defenses against fraud. Educational resources from regulators, such as the SEC’s investor alerts, are valuable for understanding existing and emerging market risks. Additionally, regularly speaking with financial professionals and trusted advisors can help you remain aware and prepared.

    Consider signing up for email alerts from regulatory authorities, attending workshops, or joining investor protection organizations. Proactive learning and networking with others can help you identify new tactics and scams as they emerge. Remember, scammers often target those who appear disengaged or uninformed. Committing to ongoing education and vigilance sets you apart and can help safeguard your hard-earned investments over the long term.

    Conclusion

    Investors face real and ever-changing threats from securities fraud, but with vigilance, the right information, and proper due diligence, you can minimize these risks. Take time to research, consult with professionals, and act swiftly if you notice something suspicious. With careful planning and awareness, you can make informed decisions, maintain confidence in your investments, and protect your financial well-being.

    Ultimately, your best defense against securities fraud is education, cautious optimism, and a willingness to seek help when necessary. By understanding the warning signs and employing the strategies outlined above, you can better navigate the markets and work toward your long-term financial goals with greater peace of mind.

    Also Read-

  • How to Prepare Financially for Unexpected Aircraft Repairs

    How to Prepare Financially for Unexpected Aircraft Repairs

    Aircraft repairs have a way of arriving without warning. One moment everything is running smoothly, and the next you’re looking at a repair bill that could ground your plans for months. 

    The good thing is that financial preparedness isn’t about predicting the unpredictable, it’s about building enough of a cushion that surprises don’t turn into disasters.

    Open a Dedicated Maintenance Savings Account

    Mixing maintenance funds with your everyday finances is a recipe for stress. A separate savings account, used strictly for aircraft upkeep, creates a clear financial boundary. 

    Even modest monthly contributions add up faster than most pilots expect, and having that cushion ready makes the difference between a quick turnaround and a grounded aircraft.

    Set Aside Funds Based on Engine and Component Age

    Older engines and aging components don’t fail on a schedule, but their repair costs tend to climb as the hours accumulate. A sensible reserve strategy ties your monthly savings directly to where your engine sits in its lifecycle.

    If your engine is approaching mid-time, your contributions should reflect that reality. The closer a component gets to its expected service limit, the more aggressively you should be saving.

    Know the Average Repair Costs for Your Aircraft Type

    Generic repair estimates won’t serve you well. Costs vary significantly depending on aircraft make, model, and the availability of parts. Spending a few hours researching what owners of your specific aircraft type typically pay for common repairs gives you a realistic target to save toward. 

    It also removes the shock factor when a quote lands in your inbox. Maintenance forums, owner groups, and parts suppliers are solid starting points for this kind of research. When researching parts and consumables, looking into AeroShell products is a practical step for understanding what lubricants and fluids your aircraft requires and what they cost. 

    Pilot John International is a well-known supplier in the aviation parts space that carries a wide range of products worth familiarizing yourself with.

    Build Relationships with Shops before Emergencies Happen

    When something breaks unexpectedly, the last thing you want to do is spend hours cold-calling repair stations to find someone who can fit you in. Owners who already have established relationships with trusted shops are in a far better position when time and urgency are both working against them.

    Visit shops during non-emergency periods. Ask questions, understand their capacity, and learn what their typical turnaround times look like. That familiarity pays off enormously when you actually need fast answers.

    Factor Reserve Requirements into Your Operating Budget

    A lot of aircraft owners calculate their operating budget around fuel, hangar, and insurance, and stop there. Repair reserves deserve a permanent line item, too. Treating maintenance savings as a fixed monthly obligation, rather than something you contribute to when you have leftover funds, changes the entire dynamic.

    The specific amount varies depending on aircraft type, age, and usage, but most experienced owners recommend setting aside somewhere between one and two percent of the aircraft’s total value each year purely for maintenance purposes.

    Conclusion

    Financial preparedness for aircraft repairs isn’t a one-time task. It’s an ongoing practice. The owners who weather unexpected repair bills with the least stress are those who started saving early, stayed informed about their aircraft’s condition, and built a support network long before anything went wrong. Start small if you need to, but start now.

    Also Read

  • Why I Chose to Handle My Divorce Without a Lawyer

    Why I Chose to Handle My Divorce Without a Lawyer

    Never imagined I’d write this stuff. And yet here I am, sharing something super personal.

    My marriage crashed last year and honestly, I was terrified about what came next because everyone around me kept pushing the same advice about getting a lawyer but my checking account was telling a completely different story which led me down this rabbit hole of researching online divorce texas options that I didn’t even know existed before.

    The Numbers Don’t Lie

    I’m kinda obsessive about tracking expenses. Lawyers wanted between $8,347 and $14,850 for what looked like glorified form-filling to me. My friend Sarah? She dropped $12,423 on her divorce and waited 14 brutal months for resolution.

    That’s literally more than I pay for housing annually (and I don’t live cheap).

    So I dug deeper into Texas law and discovered something interesting. Uncontested divorces where both people agree on major stuff can be handled without attorneys. We agreed on everything. Why throw away $200 per hour on paperwork I could potentially handle myself?

    My Experience Going the DIY Route

    Actually lived this. Here’s what went down.

    Week one involved roughly 3 hours of form completion spread across several evenings. Everything was written in normal human language instead of that legal gibberish that makes my brain hurt. I submitted documents on a Tuesday at 9:23am and received confirmation within 2 hours that formatting looked good for court filing.

    Total timeline? Exactly 67 days start to finish.

    Compare that to my coworker who’s been wrestling with lawyers for 8 months and counting. Yeah, I made the right call.

    What I Wish Someone Had Told Me Earlier

    Divorce paperwork doesn’t require a law degree to understand. I kept psyching myself out thinking I’d screw up something critical, but the guidance was actually pretty foolproof.

    The emotional acceptance part was way harder than any legal requirements. Once I processed that my marriage was actually over, paperwork became just another Tuesday task.

    And I saved approximately $10,273 by handling everything myself (yes, I calculated this obsessively). Put that money toward my apartment security deposit instead of funding some attorney’s ski trip.

    When Lawyers Actually Make Sense

    But I’m not gonna pretend online divorce works for everyone.

    Fighting over kids, property, or business assets probably means you need professional backup. I wouldn’t suggest people navigate complex disputes solo because that’s genuinely risky territory.

    My situation was straightforward though. We’d already agreed on major decisions, had zero children, and both wanted to move forward quickly. Paying lawyer fees felt like burning cash for no reason.

    Going online gave me control over timing and costs that traditional representation couldn’t match. I worked on documents at 11:47pm multiple times because that’s when I had mental space for it (definitely couldn’t schedule lawyer meetings at midnight).

    Six months later I’m settled in my new place with actual savings remaining. Sometimes the simpler path really is smarter.

    Also Read

  • RTP vs. Volatility: What Each One Actually Tells You About a Game

    RTP vs. Volatility: What Each One Actually Tells You About a Game

    Most players who know about RTP treat it as a quality score – higher is better, end of analysis. Volatility, if it gets any attention at all, gets reduced to “how risky the game feels.” Both interpretations miss the point, and using them that way leads to genuinely poor game selection.

    These two metrics measure completely different things. One tells you how much a game returns over time. The other tells you how that return is distributed across individual sessions. You need both pieces of information to make a sensible choice – because a game can score well on one and be completely wrong for your situation based on the other.

    Stake is built around crypto-native gameplay with 3,000+ slots alongside original titles like Plinko and Dice, weekly raffles with $75,000 prize pools, and a VIP program structured around active play volume – the kind of library where understanding both metrics before you browse saves real time and money.

    What RTP Actually Measures

    Return to Player is a theoretical percentage calculated across an enormous sample of spins – typically tens of millions. A 96% RTP game returns €96 per €100 wagered at that scale. The house keeps the remaining 4%.

    That figure is a property of the game’s mathematics, certified by independent labs before it reaches any casino lobby. It doesn’t fluctuate session to session. What it describes is aggregate behavior across a massive population of spins – not what happens during your two-hour Thursday session.

    The practical value of RTP is comparative. Given two otherwise similar games, the one with 97% RTP will cost you less over extended play than the one with 93% RTP. The difference compounds: playing a 93% RTP game regularly versus a 97% RTP game roughly quadruples your expected loss rate per euro wagered. That’s significant over hundreds of sessions.

    What RTP doesn’t tell you: how long your bankroll will survive, how frequently the game pays, or whether you’ll have a good time playing it. That’s volatility’s job.

    What Volatility Actually Measures

    Volatility – sometimes called variance – describes how a game’s return is distributed across individual spins and sessions. It’s the rhythm of the game, not the total.

    Low volatility means frequent small wins. Your balance moves slowly, you rarely see dramatic swings, and sessions feel relatively stable. High volatility means the opposite: long stretches of minimal returns punctuated by infrequent but potentially large payouts. The same total return gets delivered in completely different shapes.

    Here’s the critical point most explanations skip: two games with identical RTP can have completely different volatility profiles, and that difference determines whether your bankroll survives long enough to benefit from that return rate at all.

    A 96% RTP high-volatility game can run 150–300 spins with almost nothing meaningful landing. If your session budget runs out in that window, your realized return isn’t 96% – it’s whatever you happened to recover before the money ran out. The mathematical RTP becomes irrelevant if variance kills your session before it has room to breathe.

    Why You Can’t Rely on Just One

    This is where most players go wrong. They find a high-RTP game, assume it’s a good pick, and then wonder why sessions feel punishing. Or they hear that a game is “low volatility” and assume it’s the safe choice, without checking that the RTP sits at 93%.

    The combination is what matters. A 97% RTP low-volatility game is genuinely good for limited bankrolls and longer sessions – you get frequent feedback, your money lasts, and the return rate keeps losses manageable. A 96% RTP high-volatility game suits a different player entirely: one with a larger bankroll buffer who wants occasional outsized hits and can absorb the dry stretches.

    The worst combination is low RTP plus high volatility. You’re getting poor aggregate returns delivered inconsistently, with no compensating upside. These games exist in casino lobbies and tend to get dressed up with impressive maximum win figures that almost nobody ever realizes.

    Reading Both Before You Choose

    Most game information panels display RTP explicitly. Volatility is less standardized – providers use labels like low, medium, high, and very high, which aren’t precisely defined. A better approach is reading the paytable directly: if the top symbol pays 500x but three-of-a-kind pays 0.5x, that gap signals high volatility regardless of what the label says.

    For players exploring specific bonus structures – like the offers covered at $100 no deposit bonus in Australia – volatility selection matters as much as RTP during clearing. High-volatility games can eat through wagering requirements unpredictably, while low-volatility titles give you steadier progress toward withdrawal eligibility. Matching volatility to your bonus terms is an underused advantage.

    The Bankroll Connection

    Volatility determines how much bankroll you need to give a game’s RTP room to operate. As a rough guide: low-volatility games need 50–100x your average bet to run a comfortable session. Medium volatility needs 150–200x. High volatility genuinely needs 300x or more to weather expected dry patches without busting.

    This is especially relevant for players funding accounts through specific payment rails. For those using casino online Argentina pesos via MercadoPago, deposit limits can influence practical session bankrolls – which makes volatility matching to available funds more than a theoretical exercise.

    Putting It Together

    The game selection process should run in this order: eliminate anything below your RTP threshold (94% is a reasonable floor), then filter by volatility based on your actual bankroll depth and session goals. High volatility only makes sense if you have the buffer to support it – not because it sounds exciting.

    Players who use both metrics together consistently make better choices than those who chase either one alone. RTP tells you the cost of playing. Volatility tells you what that cost feels like. You need both to know what you’re actually getting into.

    Also Read

  • Why Shingle Damage Often Signals Deeper Problems Beneath the Surface

    Why Shingle Damage Often Signals Deeper Problems Beneath the Surface

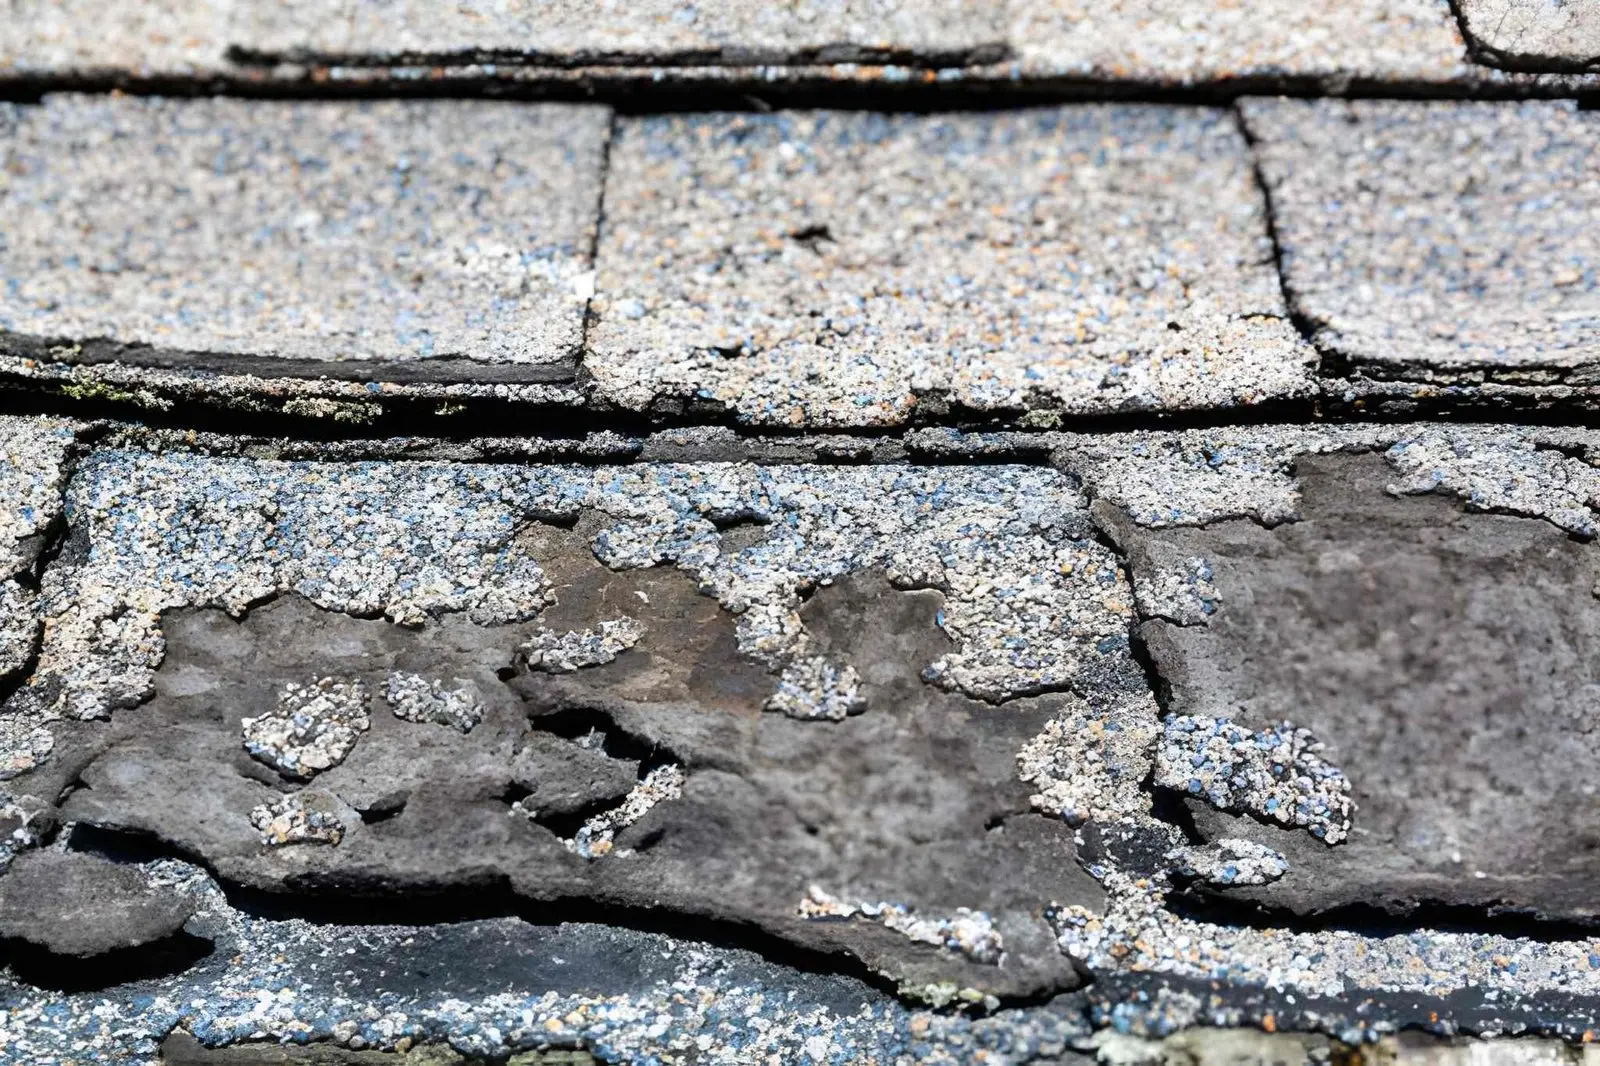
    A few damaged shingles can look like a simple fix. From the ground, it might seem like a small section just needs to be replaced. But in many cases, what is visible on the surface is only part of the issue. Shingles are the outer layer of a larger system, and when they fail, the layers underneath are often already affected. For homeowners considering roofing services Eagle Mountain, understanding what sits beneath those shingles is key to making the right repair decision.

    The challenge is that the underlying damage is not always obvious. A roof can look mostly intact while moisture has already reached the underlayment or even the decking below. By the time surface damage appears, the problem may have been developing for much longer.

    Shingles Are Not the Only Protection

    Shingles are designed to shed water, not act as the only barrier. Beneath them sits underlayment, which provides a secondary layer of protection. Below that is the roof deck, which supports the entire system. Once shingles are compromised, water can begin working its way past that outer layer.

    If the underlayment is still intact, it may slow the process. But once it begins to wear or tear, moisture can reach the decking. At that point, the issue moves beyond surface damage and becomes structural.

    Water Moves Beneath the Surface Before It Becomes Visible

    Water rarely stays at the entry point. After getting beneath the shingles, it can travel along the underlayment or decking before settling in a low spot. This is why interior stains often do not align with visible damage above.

    As moisture spreads, it affects a larger section of the roof. Fasteners can loosen, wood can soften, and materials may begin to separate. A small entry point can lead to a wider problem without obvious exterior signs.

    Underlayment Failure Allows Moisture to Spread

    Underlayment often takes the impact after shingles begin to fail. It can tear under stress, degrade from heat, or weaken after repeated exposure to moisture. Once that layer is compromised, it no longer provides reliable protection.

    Replacing surface materials alone does not resolve this condition. If the underlayment has already failed, water can continue to enter and move through the system. This is a common reason repairs do not hold.

    Decking Damage Changes the Scope of the Work

    Once moisture reaches the decking, the repair becomes more involved. Roof decking can absorb water and begin to weaken over time. Soft areas, warping, or deterioration may develop even if the surface still appears stable.

    At this stage, repairs extend beyond shingles and underlayment. Sections of decking may need to be replaced to restore the structure. Ignoring this layer often leads to continued problems after surface work is completed.

    Surface Repairs Alone Often Miss the Root Cause

    Replacing a few shingles or sealing a visible gap can stop a leak for a short time, but it does not deal with moisture that has already worked its way underneath. If the underlayment or decking has been affected, water can continue to move through those layers and show up again later. That is why the same leak often returns after a basic patch. A repair holds only when the problem below the surface is found and corrected.

    Identifying Hidden Damage

    A proper inspection goes beyond what is visible on the surface. It involves checking for soft spots in the decking, signs of moisture beneath the shingles, and areas where materials have loosened or shifted. Small irregularities, like slight dips or uneven sections, often point to deeper issues.

    The attic can confirm what is happening below. Staining on wood, damp insulation, or slight sagging usually means moisture has been present for some time. These details help show whether the problem is limited to the surface or affects the structure underneath.

    Targeted Repairs Work When Damage Is Limited

    If the underlying layers remain intact and the damage is confined to a small area, a focused repair can be effective. Replacing affected shingles and reinforcing surrounding components can restore performance. The key is confirming that moisture has not spread beyond the visible section. When the issue is contained, repairs can provide a reliable solution.

    Widespread Wear Requires a Broader Solution

    If underlayment failure or decking damage appears in multiple areas, surface repairs may not be enough. Repeated issues or multiple weak spots suggest that the roof system is wearing down more broadly. In these cases, replacing larger sections or the full system may be more practical. This approach restores all layers at once and reduces the need for ongoing repairs.

    Lasting Repairs Address the Full Roofing System

    The difference between a short-term fix and a lasting repair comes down to scope. Addressing only the surface may stop a leak briefly, but it does not prevent future problems if deeper layers are affected. Looking at the full system, including underlayment and decking, ensures the repair resolves the actual cause. This approach helps prevent repeat issues and extends the life of the roof.

    Conclusion

    Shingle damage is often the first visible sign of a deeper issue within the roofing system. What looks like a small surface problem may involve underlayment failure or decking deterioration beneath it. For homeowners considering roofing services Eagle Mountain, understanding these hidden layers helps avoid repairs that only solve part of the problem. Addressing the full system, not just the surface, is what keeps a roof performing the way it should.

    Also Read

  • The Three Situations Where I Refuse to Place a Bet

    The Three Situations Where I Refuse to Place a Bet

    Most gambling advice focuses on how to play. The more useful discipline is knowing when not to.

    There are three situations I’ve identified through fairly expensive trial and error where my bet quality collapses regardless of the game, the stake, or the session structure around it. Not occasionally – consistently. Once I mapped those situations clearly, refusing to bet in them stopped feeling like restraint and started feeling like basic competence.

    None of them are dramatic. Two happen regularly. That’s what makes them worth knowing.

    With 5,000+ games across slots, live casino, table games, and instant wins alongside a welcome package up to €4,500 + 250 free spins, Slotlords Casino is the kind of environment where all three of these situations can develop within a single session if you’re not paying attention to the conditions you’re playing under.

    Situation One: When I Don’t Know the Game’s Variance Profile

    Loading a game cold with real money and discovering its volatility profile through your own balance is one of the most consistently expensive habits in casual gambling. High-variance games in particular create a specific problem – they can run entirely cold for 150+ spins before resolving, and a player who doesn’t know that will interpret the cold streak as evidence the session is broken rather than as normal behavior.

    My rule: I don’t bet real money on any game I haven’t spent at least twenty minutes in demo mode first. Not to learn a strategy – slots don’t have one – but to calibrate what normal looks like. What’s the typical gap between feature triggers? How often do wins actually land in the base game? Does the balance trend steadily or swing dramatically?

    The free mode for something like sugar rush 1000 demo illustrates why this matters in practice. The 1000 variant concentrates returns heavily into multiplied scatter combinations – base game spins outside those sequences contribute very little. Without that context, a twenty-minute cold patch in real play feels like the game isn’t working. With it, you’re just waiting for the variance to resolve. Same session, completely different decision-making.

    Situation Two: When I’m Trying to Recover a Previous Loss

    This one is harder to admit than the first, but it’s the situation that has cost me the most money over time. There’s a specific mental state that arrives roughly fifteen minutes after a significant loss – call it recovery mode – where the primary session goal shifts from enjoying the game to getting back to even.

    Recovery mode produces worse decisions than almost any other psychological state. Stake sizing becomes reactive. Game selection becomes about what “feels ready to pay” rather than what suits my bankroll. Session length extends indefinitely because stopping while down feels like accepting a loss that hasn’t been finalized yet.

    The tell is simple: if I catch myself thinking about what I lost in the previous session while I’m deciding whether to start a new one, I don’t bet. Not that day. The urge to recover is strong evidence that the next session will be driven by the wrong motivation, and that evidence has never once been wrong in my experience.

    Situation Three: When I’m Unclear on the Platform’s Withdrawal Conditions

    This applies specifically to new platforms rather than established ones, and it’s less about responsible gambling than about basic financial clarity. I won’t bet real money on a platform I haven’t verified can actually return funds reliably and without obstacles I haven’t accounted for.

    The specific things I check before betting on an unfamiliar site: withdrawal processing times, whether KYC requirements have been completed upfront or only triggered at cashout, and whether the platform’s licensing creates any restrictions on my account. Comparative coverage of platforms like those listed under online casinos ohne OASIS – casinos operating outside Germany’s OASIS self-exclusion database – highlights how licensing framework affects the practical withdrawal experience, not just the responsible gambling tools available. Understanding that before depositing avoids discovering it after winning something worth withdrawing.

    What These Three Have in Common

    None of them are about the game itself. Two are about my internal state, one is about the environment I’m playing in. That’s not a coincidence – the situations that reliably produce bad bets are almost never about the odds or the mechanics. They’re about the conditions under which the decision is being made.

    Recognizing those conditions early enough to act on them is the part nobody teaches. It’s also the part that separates a player who improves from one who keeps repeating the same expensive sessions.

    Also Read